
 2024-01-18
 617
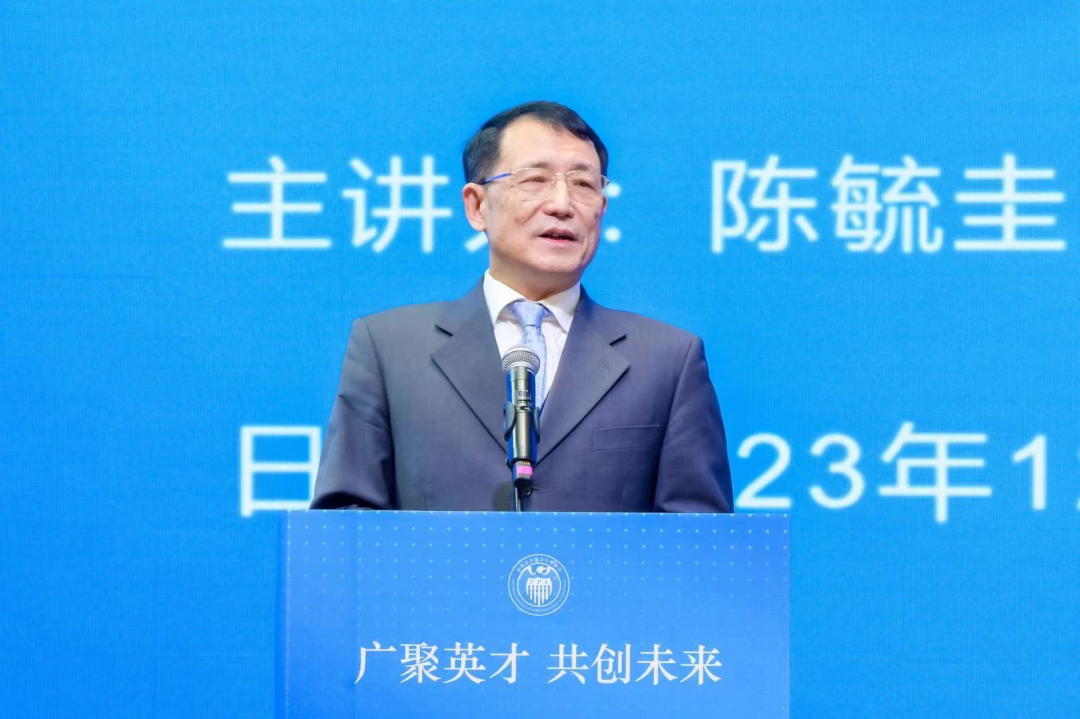
I. Supply dimension of the CPA industry and high-quality development of accounting professional service capabilities
From the perspective of supply side, the economic nature of the CPA industry as a professional service industry is an important starting point for understanding and taking action to promote the high-quality development of the CPA industry.
As a starting point for understanding, it is not difficult to see that there is a gap between the professional service capabilities of the CPA industry and the public's expectations. In the audit field, this gap manifests as an inadequate ability to detect significant misstatements in financial reports. In the consulting field, it manifests as an inadequate ability to provide innovative solutions for economic and social life.
As I have stated many times before, the deficiencies mentioned here are not industry-wide or undifferentiated deficiencies, but rather deficiencies in the sense of unevenness, manifested as differences between certified public accountants (CPAs) and between institutions, as well as differences between divisions and branches of institutions, and also manifested in other aspects that determine the professional service capabilities of the CPA industry.
Based on this judgment, we should have confidence in the future of high-quality development of the CPA industry. This is because we already have a group of CPAs and institutions capable of providing high-quality accounting professional services. The CPA industry in China is capable of achieving high quality, and the CPA industry in Shenzhen is also capable of achieving high quality.
As a starting point for action, to promote the high-quality development of the CPA industry, the first step should be the high-quality development of professional service capabilities. Without the high-quality development of professional service capabilities, all efforts aimed at the high-quality development of the CPA industry will become aimless. In terms of action strategies for the high-quality development of the CPA industry, we should focus on filling gaps and making up deficiencies, rather than grasping at everything. We should identify what is done well and what is not. For those who do well, we should commend them, promote them to the public, set them as benchmarks for others to learn from; for those who do not do well, we should urge them to improve and move towards the ranks of high-quality. Whoever has deficiencies should be responsible for filling gaps and making up deficiencies; where there are deficiencies, efforts should be made in that area.
The "Industry Development Plan for Certified Public Accountants (2021-2025)" formulated by the China Certified Public Accountants Association includes six articles. I recommend them as the main areas for the high-quality development of professional service capabilities in the CPA industry. These include continuously strengthening the construction of industry integrity, promoting the improvement of the industry's legal system, perfecting talent cultivation mechanisms, fostering high-quality accounting firms, continuously enhancing industry supervision, and deeply promoting the informatization of the industry. Among these six articles, integrity construction, talent construction, and accounting firm construction refer to the construction of service entities; informatization is technical support, empowerment, and innovation and upgrading of service technology; legal system, standards, and supervision refer to the construction of systems and external governance systems.
The high-quality development of accounting firms, or, to use the term from the five-year plan, the construction of high-quality accounting firms, is marked by the high quality of the quality management system. The pain point lies in the persistent failure to improve the quality of the quality management system. The basis for constructing and even evaluating the quality management system is the three audit standards: No. 5101, No. 5102, and No. 1121. These three professional standards in quality management were issued by the Ministry of Finance in December 2020, namely, "Quality Management Standards for Accounting Firms No. 5101 - Business Quality Management," "Quality Management Standards for Accounting Firms No. 5102 - Project Quality Review," and "Auditing Standards for Chinese Certified Public Accountants No. 1121 - Quality Management for the Audit of Financial Statements." Accounting firms engaged in securities services have started implementing these standards since January 1, 2023. The "five unifications" advocated by us for many years are actually colloquial terms for the quality management system. Certified public accountants often tell me that they have unified their revenue and expenditure accounting and salary standards. I say that these two aspects are important, but the key is not here. The key lies in the unification of the quality management system. Here, I would like to update my viewpoint: the high-quality development of the quality management system should be regarded as the key task for the high-quality development of accounting firms.
The CPA industry provides accounting professional services, and correspondingly, there is an issue of quality supervision and a matter of service responsibility, which is regulatory enforcement. The significance of regulatory enforcement for the high-quality development of accounting professional services lies in accurately identifying service quality and reasonably attributing service responsibilities. Otherwise, if good and bad are not distinguished, high-quality services cannot be recognized, poor quality services cannot be punished, and the extent of service responsibilities cannot be reflected, then the guidance towards high-quality development becomes problematic. Based on my personal experience, the starting point for regulators and judicial authorities to do their work well is beyond doubt. They respect the authority of CPA professional standards and have sincerity in safeguarding the legitimate rights and interests of CPAs. Of course, it is also necessary to recognize the urgent requirement of high-quality development of the CPA industry for high-quality development of regulatory enforcement, and continuously improve the professionalization and standardization level of regulatory enforcement. The professionalization level of regulatory enforcement mentioned here refers to the cadre team of regulatory enforcement, while the standardization level of regulatory enforcement refers to the organizational setup and coordination of division of labor in regulatory enforcement. The main problem of the latter is multiple inspections and repeated inspections. Can we consider better and higher-quality division of labor among departments? For example, the capital market regulatory department focuses on investigating and handling cases involving listed companies, while the competent department of the accounting industry focuses on investigating and handling cases involving state-owned enterprises and non-listed companies. The daily practice quality supervision can be handed over to the CPA association, and at the same time, coordination among various levels within the department should be improved.
The aggregation of civil liabilities is a crucial area of regulatory enforcement. In the past, there were indeed some biased precedents, albeit few in number, which caused severe anxiety among certified public accountants (CPAs). Fortunately, this issue has garnered significant attention from judicial authorities, and the situation is improving. At least, regulators, judicial authorities, the industry, and the public have reached a fairly clear consensus: CPAs who fail to conduct audits in accordance with professional standards and thus fail to detect material misstatements in financial reports should be held accountable in three distinct scenarios. In cases of collusion and fraud, joint liability shall be imposed; in cases of gross negligence, proportional liability shall be imposed depending on the severity and circumstances; and in cases of ordinary negligence, no civil liability shall be pursued.
For anything, it is necessary to say two sentences to conform to dialectics. Apart from the above sentence, I want to share with my comrades the second sentence, which is about correctly understanding the reasonable assurance in CPA auditing. It is correct to say that reasonable assurance is not absolute assurance, but we should not exaggerate this point. Reasonable assurance is relative to absolute assurance, emphasizing that auditing "does not provide absolute assurance". Obviously, reasonable assurance is not a low level of assurance; it is a high level of assurance. We cannot use vaguely interpreted reasonable assurance to justify gross negligence. In summary, we should correctly understand the meaning of reasonable assurance, gradually narrow and even eliminate the gap between public expectations by improving the level of reasonable assurance. This should be positioned as the goal for the high-quality development of accounting professional services.
II. Market Dimensions of the Certified Public Accountant Industry and High-quality Development of the Accounting Services Market
High-quality services cannot be separated from a high-quality market. A high-quality market is one that can distinguish between good and bad products, and one where good services can command good prices. Whether in Shenzhen or other provincial and municipal markets, the audit and consulting fees charged by certified public accountants (CPAs) are too low, both compared to international peers and other professional services. The low fees charged by CPAs for audit and consulting services are a sign of insufficient quality in the accounting services market and an obstacle to the high-quality development of accounting services. In efforts to promote the high-quality development of the CPA industry, it is important to place the construction of a high-quality accounting services market in a prominent position.
The primary reason for the low fees charged for accounting services is the insufficient recognition of the value of accounting services. Specifically, there are two typical manifestations. Some comrades believe that hiring certified public accountants (CPAs) for audits is mandatory by law, and there's nothing they can do about it. Since they have no choice but to hire, they might as well make do with it, spending as little money as possible and making it as easy as possible to talk about.
Some comrades argue that audit reports are just a few pieces of paper, so why should they cost hundreds of thousands, millions, tens of millions, or even billions? A chairman or general manager earns only those salaries and bonuses in a year, so why should they pay such a large sum to certified public accountants (CPAs) for auditing? As a result, they desperately try to drive down the price. They believe that CPA auditing is merely a statutory requirement, and view hiring CPA auditing as a last resort. They think that auditing is not worth much money, only seeing a few paragraphs in the CPA audit report, without seeing the resources invested and risks borne by CPAs, audit teams, and their institutions to complete the audit work with high quality. They fail to recognize the compliance value of auditing, and do not see the credit enhancement value, pricing value, risk avoidance value, and knowledge value of CPA auditing.
The foundation of the market lies in integrity, and CPA auditing is a crucial link in the integrity chain. CPA auditing provides reasonable assurance regarding the authenticity and fairness of accounting information, thereby enhancing the confidence of the public and regulatory bodies in such information. With financial reports audited by CPAs, investment and credit transactions become easier to facilitate, reflecting the credit enhancement value of CPA auditing. Additionally, CPA auditing possesses pricing value. In the eyes of investors, accounting firms offering audit services are reputable, making financial statements more credible and investment risks correspondingly lower. Consequently, financial instruments such as stocks and bonds enjoy lower risk premiums. This proposition has been widely proven in academic circles.
Certified public accountant (CPA) audits also serve a hedging function. Identifying fraudulent activities that lead to material misstatements is a crucial aspect of CPA audits. CPA audits assist corporate governance and management in preventing and addressing investment risks, operational risks, asset risks, and various other risks.
The value of knowledge refers to the value of the CPA profession as an expert profession. Economic analysis shows that the return of a profession is positively correlated with the professional growth cycle of its practitioners. If college graduation is taken as the starting point of professional growth, some professions can be quickly mastered. However, for the expert profession of CPA, passing the professional examination is only a starting point. It takes years of practical experience to become a CPA. To become a partner, it requires more than ten years or even longer accumulation. Even if one has become a CPA and a partner, they still need to receive continuing education, continue learning, and engage in lifelong learning. The audit fees charged by CPAs should reflect the value of knowledge.
In promoting the high-quality development of the professional services market for certified public accountants, it is crucial to effectively promote the value of CPA audits and explain to the public its credit enhancement value, pricing value, risk aversion value, and knowledge value.
The high-quality development of the accounting professional services market also involves the issue of a high-quality trading mechanism, with the most prominent being the price competition in CPA audit services. Price competition in the CPA industry is an important factor affecting audit quality, as it undermines the independence of CPA audits and reduces audit quality. It should be said that in the market domain, competition is often regarded as ensuring that customers receive the lowest-priced and highest-quality goods and services, which is a manifestation of market efficiency. However, this principle does not fully apply to the accounting professional services market. Because the final service product delivered by CPAs is an audit report, audit clients, investors, regulators, and stakeholders generally cannot intuitively perceive how much effort and work CPAs have put into completing the audit report. Often, due to financial fraud, business failures, and corporate bankruptcies of audit clients, audit failures occur, and users of audit reports suddenly realize that the audit report does not meet the requirements, indicating that there may be serious issues with audit quality. However, by this time, the situation has already changed, and the losses incurred by stakeholders are difficult to recover.
The market often selects certified public accountants (CPAs) through bidding. In many cases, the demand side tends to place great emphasis on price, and "the lowest bidder wins" has become a common phenomenon. In the view of the CPA industry, price competition inevitably leads to a decline in quality services, damaging the mutual trust between the CPA industry and audit clients. If the bidding system does not curb price competition and becomes a price war without quality basis, high-quality services will lose their opportunities, resulting in the displacement of good money by bad money. The bidding system based on "the lowest bidder wins" has been widely criticized, especially in professional service markets such as CPA auditing. One of the many tasks for the high-quality development of the CPA professional service market is to establish a government procurement system that matches professional services including CPA auditing. I am pleased to see that from the central to local levels, party and government departments at all levels have attached importance to the significance of the government procurement system for high-quality development and the negative impact of "the lowest bidder wins". We have reason to expect new policy progress in this area.
The "Action Plan for Accelerating the High-quality Development of the Certified Public Accountant and Asset Appraisal Industries in Shenzhen (2023-2025)" issued by the Shenzhen Finance Bureau has several provisions specifically targeting market construction, which I strongly support. For instance, Article 8 encourages various departments to standardize the procurement of accounting and appraisal professional services based on business needs, emphasizing quality factors rather than quotation levels as the main weighting factor. Another example is Article 22, which fully leverages the role of the unified regulatory platform for the certified public accountant industry, intensifying efforts to crack down on illegal and irregular behaviors such as certified public accountants practicing under a false name, practicing beyond their competence, accounting firms selling audit reports online, operating without a license, and engaging in cut-throat low-price competition. I am looking forward to seeing the effectiveness of this three-year action plan by the Shenzhen Finance Bureau in promoting high-quality development in the accounting service market.
III. Professional Dimensions of the Certified Public Accountant Industry and High-quality Development of Accounting Service Talents
I advocate viewing the CPA industry from a professional perspective for two reasons. Firstly, the significance of CPAs to the CPA industry, and even to accounting firms, is decisive. Only with CPAs can there be a CPA industry and accounting firms. As human capital, CPAs constitute almost all of the core resources of the CPA industry and accounting firms. Secondly, as human capital, CPAs are not merely a physical collection of numerous CPAs, but rather a professional group with a common knowledge structure and skill set, as well as a shared professional ethos and responsibility. CPAs should be viewed from a professional perspective.
The first reason above implies that the high-quality development of the CPA industry primarily hinges on the high-quality development of CPA talents. The construction of CPA talents is not merely one of the six elements of accounting professional service capability building, but should even be synonymous with accounting professional service capability. The second reason suggests that the high-quality development of CPA talents should follow the path of professionalization for CPAs.
As the main bearer of the professionalization of certified public accountants, it is important for them to focus on enhancing their professional qualities in three aspects: professional ethics, professional knowledge, and specialized skills. They should cultivate the ability to identify significant misstatements in financial reports and develop the capacity to provide reasonable assurance.
Professionalism is the core of the professional quality of certified public accountants (CPAs). The professionalism of CPAs has two levels of implications. The first level is at the personality level, which includes independence, objectivity, and impartiality. The second level is at the behavior level, which includes prudence, diligence, professional skepticism, competence, and proper conduct. These two levels of professionalism imply that CPAs should be individuals with noble character, or at least individuals who act with prudence.
In the process of promoting the professionalization of certified public accountants, emphasis should be placed on cultivating a large number of high-quality, versatile, and international talent teams. Specifically, firstly, we should cultivate high-quality talents who serve specific service targets such as large financial institutions, high-tech and Internet enterprises, facing major national needs, technological frontiers, main economic battlefields, and emerging fields; secondly, we should cultivate versatile talents in specialized fields such as digital technology development, information system auditing, financial instrument valuation, actuarial science, and internal control; thirdly, we should cultivate international talents with international qualifications, international vision, and international recognition for Chinese enterprises to "go global" and the construction of the Belt and Road Initiative, as well as for overseas capital markets.
Some certified public accountants (CPAs) complain that the requirements for this profession are too high and the audit standards are too strict. In fact, the high professional requirements and strict audit standards are inherent in the CPA audit system. CPA auditing is, to a considerable extent, a public welfare work, which is precisely why the qualification licensing and market monopoly of CPAs have been retained despite the significant reforms in "streamlining administration, delegating powers, and improving regulation" over the past few years. Qualification licensing and market monopoly are professional powers, while high requirements and strict standards are professional responsibilities. Power and responsibility should be matched. Comrades should view this issue calmly, fairly, and rationally, and must not only enjoy statutory powers but also forget the responsibilities entrusted by the party and the people. Comrades in the industry should regard deepening the understanding of CPA professionalism and professional responsibility as the main responsibility for the high-quality development of the CPA industry, and as the first step in the high-quality development of CPA talent.
In addition to CPA (Certified Public Accountant) professionals, who naturally bear the responsibility of self-improvement as the main actors in the professionalization of CPA, the professionalization of CPA also requires the support of a high-quality professional system. The professional system includes five aspects: professional access, professional standards, professional education, professional supervision, and professional organizations. As a professional organization, the CPA association is not only a part of the professional system but also the main body for the construction, promotion, and implementation of the other four aspects of the professional system. It plays a very important role in the process of professionalization of CPA. In the high-quality development of the CPA industry, the high-quality development of the CPA association should be emphasized.
That's all I have to say. Thank you, everyone.
 Official WeChat
 Official WeChat
