
 2020-12-07
 295
I. Why was this Announcement issued?
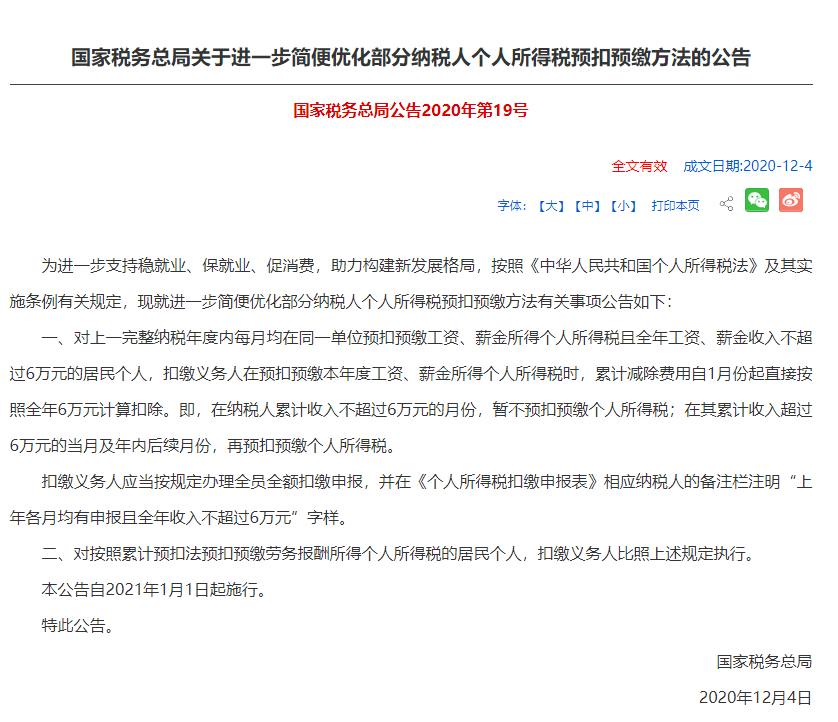
In this regard, considering that a full tax year has passed since the implementation of the new tax system, and taxpayers now have full‑year income tax data under the new system, for this group of stable workers with annual income below RMB 60,000, on the basis of the existing tax reform benefits, the withholding and prepayment method can be optimised to further reduce their tax compliance burden. In accordance with the relevant provisions of the Individual Income Tax Law of the People's Republic of China and its implementing regulations, and after considering both the tax burden on taxpayers during the withholding stage and the stability of fiscal revenue, this Announcement has been issued. It also helps to better support stable employment, protect employment, promote consumption, and facilitate the construction of a new development pattern.
The Announcement mainly optimises the withholding and prepayment methods for two categories of taxpayers:
Second, resident individuals whose individual income tax on remuneration for labour services is withheld and prepaid under the cumulative withholding method, such as insurance sales agents and securities brokers. Similarly, they must simultaneously meet the following three conditions: (1) in the previous tax year, from January to December, they received remuneration from the same employer and filed withholding and prepayment declarations for individual income tax on remuneration for labour services under the cumulative withholding method; (2) the cumulative remuneration for labour services for the previous tax year (without deducting any expenses or tax‑exempt income) did not exceed RMB 60,000; (3) from January of the current tax year, they continue to receive remuneration for labour services from the same employer for which tax is withheld and prepaid under the cumulative withholding method.
[Example] Xiao Zhao worked at Employer B from March to December 2020, with an annual wage income of RMB 54,000. Assuming Xiao Zhao continues to work at Employer B in 2021, because he did not work there for the entire previous year, this Announcement does not apply.
For taxpayers who meet the requirements of the Announcement, when withholding agents withhold and prepay individual income tax for the current tax year, the accumulated deduction shall be calculated directly based on the annual amount of RMB 60,000 starting from January. That is, in months where the taxpayer's accumulated income does not exceed RMB 60,000, no individual income tax shall be withheld or prepaid; in the month when the accumulated income exceeds RMB 60,000 and in subsequent months of the year, individual income tax shall be withheld and prepaid. At the same time, in accordance with the tax law, withholding agents are still required to handle full‑amount withholding declarations for all employees as stipulated by the tax law.
[Example] Xiao Zhou is an employee of Unit A. From January to December 2020, he received wages and salaries of RMB 50,000 from Unit A, and the unit filed detailed full‑amount declarations for individual income tax on wages and salaries for January‑December 2020. In 2021, Unit A pays him a monthly salary of RMB 8,000, and he contributes RMB 2,000 per month to "three insurances and one fund" according to national standards. Without considering other deductions, under the original withholding and prepayment method, Xiao Zhou would need to prepay RMB 30 in individual income tax each month. Using the new withholding and prepayment method provided in this Announcement, from January to July, because his accumulated income (RMB 8,000 × 7 months = RMB 56,000) is less than RMB 60,000, he does not need to pay tax; from August onwards, his accumulated income exceeds RMB 60,000, and the monthly withholding and prepayment tax amounts are calculated as follows:
September withholding tax = (8000×9 - 2000×9 - 60000) × 3% - 0 = RMB 0
November withholding tax = (8000×11 - 2000×11 - 60000) × 3% - 0 = RMB 180
It should be noted that for taxpayers who meet the conditions of this Announcement, if the withholding agent expects that the income to be paid to them in the current year will exceed RMB 60,000, or if the taxpayer needs a tax record, or if their combined income from multiple sources is expected to exceed RMB 60,000 for the year, the withholding agent and the taxpayer may, after mutual confirmation before the withholding declaration for January of the current year, calculate and prepay the individual income tax using the original withholding and prepayment method.
IV. After the Announcement is issued, how should withholding agents operate?
V. When does the Announcement take effect?
Link: "Announcement of the State Administration of Taxation on Further Simplifying and Optimising the Withholding and Prepayment Method for Individual Income Tax for Certain Taxpayers" (Announcement of the State Administration of Taxation [2020] No. 19)
Source: State Administration of Taxation
 Official WeChat
 Official WeChat
