
 2020-12-04
 295
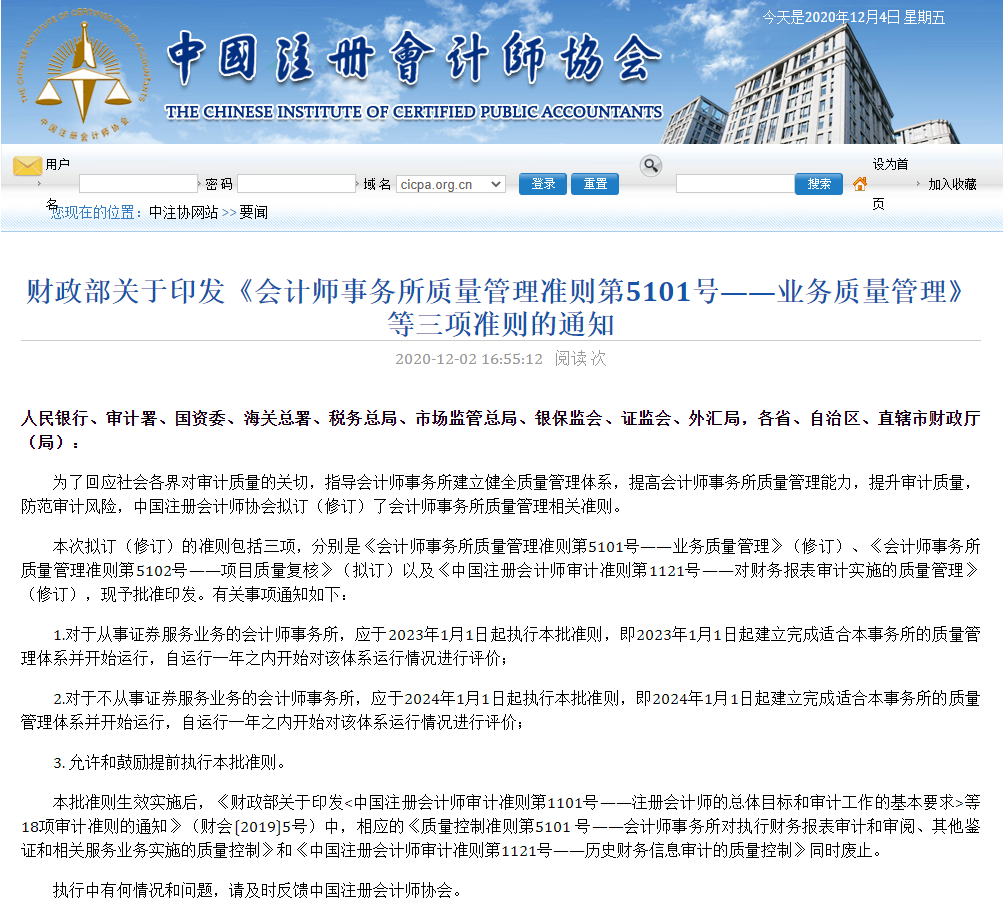
To the People's Bank of China, the National Audit Office, the State-owned Assets Supervision and Administration Commission, the General Administration of Customs, the State Administration of Taxation, the State Administration for Market Regulation, the China Banking and Insurance Regulatory Commission, the China Securities Regulatory Commission, the State Administration of Foreign Exchange, and the finance departments (bureaus) of all provinces, autonomous regions, and municipalities directly under the central government:
In response to the concerns of all sectors of society about audit quality, and to guide accounting firms to establish and improve quality management systems, enhance their quality management capabilities, improve audit quality, and prevent audit risks, the Chinese Institute of Certified Public Accountants has drafted (revised) the relevant quality management standards for accounting firms.
The three standards drafted (revised) this time are: "Quality Management Standard for Accounting Firms No. 5101 – Quality Management of Engagements" (revised), "Quality Management Standard for Accounting Firms No. 5102 – Engagement Quality Review" (drafted), and "China Standard on Auditing for Certified Public Accountants No. 1121 – Quality Management for Audits of Financial Statements" (revised). They are hereby approved for issuance. The relevant matters are notified as follows:
1. For accounting firms that engage in securities service business, these standards shall be implemented from January 1, 2023, that is, they shall establish and begin operating a quality management system suitable for the firm from January 1, 2023, and shall begin to evaluate the operation of the system within one year of operation;
2. For accounting firms that do not engage in securities service business, these standards shall be implemented from January 1, 2024, that is, they shall establish and begin operating a quality management system suitable for the firm from January 1, 2024, and shall begin to evaluate the operation of the system within one year of operation;
3. Early implementation of these standards is permitted and encouraged.
After these standards take effect, the corresponding "Quality Control Standard No. 5101 – Quality Control for Firms that Perform Audits and Reviews of Financial Statements, and Other Assurance and Related Services Engagements" and "China Standard on Auditing for Certified Public Accountants No. 1121 – Quality Control for Audits of Historical Financial Information" in the "Notice of the Ministry of Finance on Issuing 18 Auditing Standards including China Standard on Auditing for Certified Public Accountants No. 1101 – Overall Objectives of the Auditor and the Basic Requirements of an Audit" (Cai Kuai [2019] No. 5) shall be simultaneously repealed.
Any circumstances and problems encountered during implementation shall be reported to the Chinese Institute of Certified Public Accountants in a timely manner.
Appendices:
1. Quality Management Standard for Accounting Firms No. 5101 – Quality Management of Engagements
2. Quality Management Standard for Accounting Firms No. 5102 – Engagement Quality Review
Ministry of Finance
November 19, 2020
Original link:
http://kjs.mof.gov.cn/zhengcefabu/202012/t20201202_3632177.htm
 Official WeChat
 Official WeChat
